First-Time Home Buyer
Buying Your First Home in Langley?
Buying your first home is easier when the mortgage planning starts before the property search gets serious.
I help first-time buyers in Langley understand affordability, down payment, closing costs, pre-approval, and what needs to happen once the right property comes along.
Before You Start Shopping
Know what fits before you fall in love with the home.
What price range feels comfortable
How much cash you need before closing
What the lender needs to review
How the property itself may affect financing
The goal is not simply to qualify for the biggest mortgage. It is to understand what works for you.
First-Home Planning
Buying gets easier when the numbers come before the listings.
Langley offers everything from condos and townhomes to detached homes, newer developments, and rural properties. Knowing your mortgage boundaries first makes it easier to decide which part of that market fits.
Start With Affordability
Understand both what you may qualify for and what monthly payment actually feels comfortable.
Know the Cash You Need
Plan for the down payment, deposit, closing costs, and money you still want available after possession.
Get the Mortgage Side Organized
Review income, employment, debts, credit, and down payment sources before the purchase becomes urgent.
Then Look at the Property
Consider how strata, new construction, rural servicing, suites, or other property details may affect financing.
You do not need to be ready to make an offer next week to start planning. Starting earlier can give you more options.
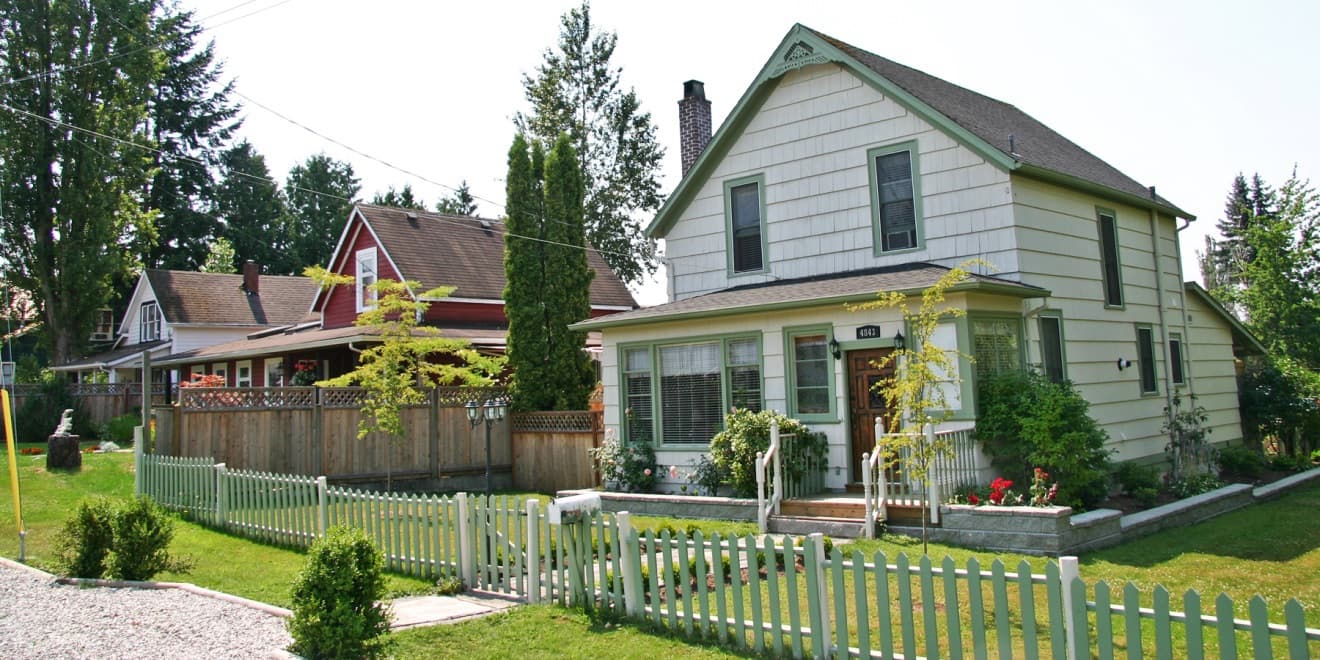
Buying in Langley
The right first home is the one that fits both the mortgage and the life you want after you move in.
Down Payment & Closing Costs
Your down payment is only part of the cash you need.
First-time buyers often focus on the down payment, but the full plan also needs to account for the deposit, legal costs, adjustments, property transfer costs when applicable, and other closing expenses.
New construction can also bring additional timing and tax considerations, so it is worth understanding the full cash requirement before committing.
Before you make an offer, know:
Where the down payment is coming from
How long the funds have been in the account
Whether any portion is a gift
How much is needed for closing costs
How much you want left after closing
Keep some breathing room.
Buying your first home is easier when closing day does not use every dollar you have saved.
Affordability
What you qualify for and what you want to spend are not always the same number.
A lender looks at income, debts, credit, down payment, and qualifying rules. That produces a mortgage limit.
Your real-life budget also needs to leave room for strata fees, property taxes, utilities, transportation, savings, travel, hobbies, kids, pets, and everything else that still exists after you buy the home.
Use the Income Required CalculatorThe Number I Want to Know
What monthly payment lets you own the home and still have room for the rest of your life?
Comfort matters too.
I would rather build the purchase around a manageable payment than simply work backwards from the highest price a lender may approve.
Mortgage Pre-Approval
A pre-approval gives you a starting point, not a final yes.
A good pre-approval helps establish a price range and identifies mortgage questions before you start making offers.
But the actual property still needs to work. The lender may need to review the purchase contract, property type, appraisal, strata, insurance, and other details before final approval.
A Pre-Approval May Review
Income and employment
Current debts
Credit history
Down payment source
Mortgage qualification
Do not treat a pre-approval as permission to remove financing conditions before the lender has reviewed the specific property and transaction.
The Property Matters Too
Getting approved as a buyer does not mean every Langley property is automatically financeable.
Langley has an unusually broad mix of housing. The property can change the financing even when nothing about your income, debts, or down payment has changed.
Condos
Strata fees, documents, insurance, building condition, and lender acceptance can all matter.
Townhomes
A common first-home option in Langley, but strata and property-specific review still apply.
Detached Homes
The home, lot, condition, appraisal, and any secondary suite may become part of the lender review.
Rural or Less Typical Properties
Acreage, wells, septic systems, outbuildings, zoning, and property use may require closer review.
After Your Offer Is Accepted
This is where the pre-approval becomes a real mortgage application.
Once you have an accepted offer, the lender can review the actual property, purchase contract, updated documents, down payment, and anything else required for final approval.
This is why enough time for a financing condition matters. The lender may need an appraisal, strata documents, insurance information, or clarification about the property before approval is complete.
Pre-approval helps you prepare to buy.
Final approval happens after the lender has reviewed the property and the full transaction.
Do not assume the financing is finished too early.
First-Time Buyer Programs
Understand the programs before you need the money.
First-time buyer programs can help, but eligibility, withdrawal timing, documentation, and how the funds reach the purchase all matter.
First Home Savings Account
If you qualify, an FHSA may be part of your down payment savings strategy.
Home Buyers' Plan
Eligible buyers may be able to use qualifying RRSP funds toward a first-home purchase.
Property Transfer Tax
Some first-time buyers may qualify for available property transfer tax relief, depending on the purchase and eligibility rules.
Other First-Time Buyer Benefits
Other federal or provincial programs may also be available depending on your situation and the property.
Plan the withdrawals too.
It is worth sorting out the timing and documentation early so your down payment is ready when the purchase needs it.
First-Home Example
Purchase price is only one number in the plan.
Here is a simple illustration of how a first-home purchase can look once you include more than the down payment.
Purchase Price
$700,000
Down Payment
$55,000
Mortgage Before Insurance
$645,000
Illustrative Closing Costs
$13,000
Illustrative Cash Needed
$68,000
This example combines the down payment and illustrative closing costs. Actual costs and mortgage insurance will depend on the property, purchase structure, and buyer circumstances.
The goal is not just to make the purchase work on paper. It is to make sure the mortgage still feels manageable once you are actually living in the home.
First-Time Buyer Resources
You do not need to solve every part of buying your first home at once.
Mortgage Tool
Calculate your down payment
See how minimum down payment changes at different purchase prices.
Use the Down Payment CalculatorMortgage Tool
Estimate your closing costs
Plan for the costs that may need to be paid in addition to the down payment.
Estimate Closing CostsMortgage Minute
Understand mortgage pre-approval
Learn what a pre-approval can tell you and why final approval still depends on the property.
Read About Pre-ApprovalBuying Process
Follow the home-buying process
Understand what happens from planning and pre-approval through offer, conditions, and completion.
See the Home Buying ProcessLocal Guide
Explore buying in Langley
Learn more about Langley City, the Township, neighbourhoods, property types, and local considerations.
See the Langley GuideFirst-Time Buyer Guide
Go deeper into first-home planning
Explore affordability, down payment, financing, offers, closing, and first-time buyer planning in more detail.
Read the First-Time Buyer GuideLangley First-Time Buyer Questions
Questions you may have before buying your first home.
First-Time Home Buyer in Langley
You do not need to have everything figured out before we talk.
If buying your first home is somewhere on the horizon, we can start with the numbers and work out what needs to happen next.
Help Me Plan My First HomeWe can start with:
A realistic price range
How much cash you need
What the lender will review
What needs to happen before you make an offer
Starting early is completely fine. You do not need to be ready to buy tomorrow.