Buying Your First Home in Mission?
Your first mortgage should start with more than a maximum approval. I can help you work out what fits your income, savings, monthly budget, and the type of Mission property you are actually considering.
The goal is to understand the mortgage before the right property appears, so you can make decisions with fewer surprises.
Start With the Numbers
Know what fits before you fall in love with the property.
A comfortable purchase price
Down payment and closing cash
What the lender needs to approve
Whether the property itself works for financing
The biggest mortgage you can qualify for is not always the mortgage you will be happiest carrying.
Plan Before You Shop
Buying gets easier when the numbers come before the listings.
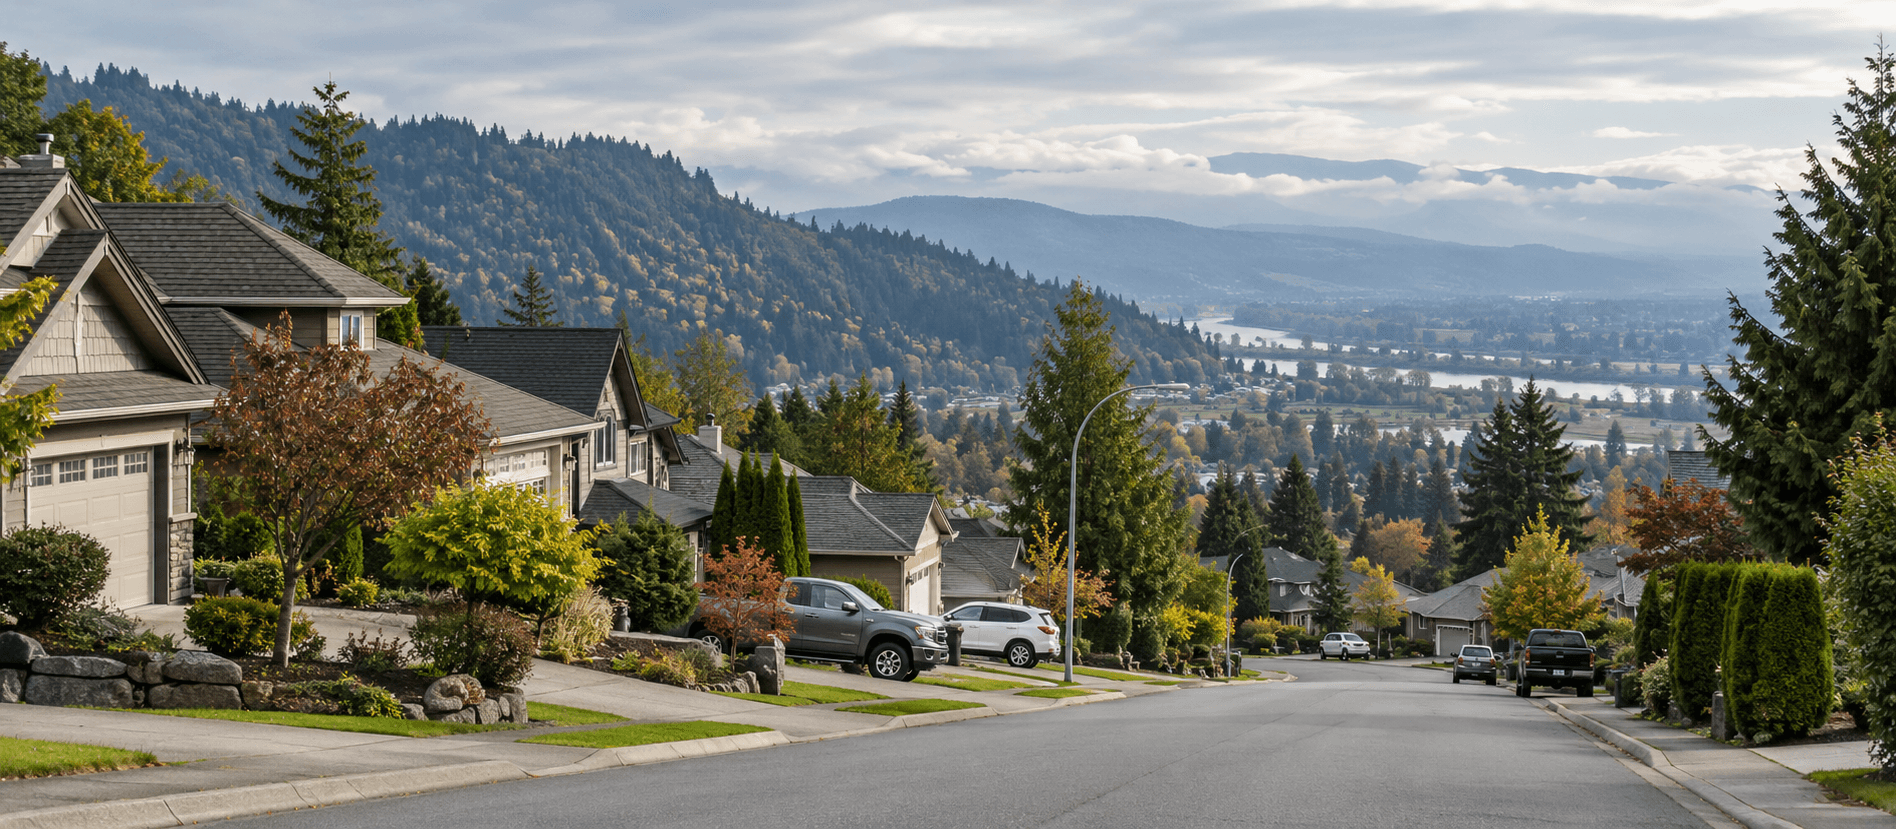
Mission offers a wide mix of housing, from condos and townhomes to detached homes, acreages, and rural properties. That means the mortgage conversation can change considerably depending on what you are looking at.
Starting early gives us time to work through the budget, documents, and property questions before an offer creates a deadline.
Start with affordability
Look at income, debts, monthly housing costs, and the payment that leaves room for the rest of your life.
Confirm the cash you need
The down payment is only part of the money needed. Closing costs and a little breathing room after possession matter too.
Review the mortgage side
Income documents, credit, debts, and the source of the down payment should be understood before you are under pressure.
Then look at the property
A condo near the core, newer detached home in Cedar Valley, home near water in Hatzic, or rural acreage can each bring different lender considerations.
Down Payment & Closing Cash
The down payment is not the only cash you will need.
First-time buyers often focus on the down payment, but there are other costs that need to be planned for before completion.
Legal costs, inspections, property tax adjustments, moving costs, and other closing expenses can all affect how much cash should stay available outside the down payment.
Leave yourself some breathing room
Putting every available dollar into the purchase can leave the first few months of homeownership unnecessarily tight.
Know where the down payment is coming from
Savings, gifts, registered accounts, and other sources may need supporting documents as part of the mortgage process.
Affordability
Qualification and comfort are two different numbers.
A lender may approve a certain mortgage amount, but that does not automatically mean the resulting monthly costs fit the way you want to live.
In Mission, the monthly picture can also change depending on the property. Strata fees, commuting, heating, insurance, wells, septic systems, and maintaining a larger lot can all matter.
Try the Income Required CalculatorLook Beyond the Mortgage
What monthly cost still leaves room for your life?
Mortgage payment
Property taxes
Strata fees when applicable
Utilities and insurance
Transportation and commuting
Property maintenance and servicing
Savings and everyday life
Pre-Approval
A pre-approval is a starting point, not the final mortgage.
A pre-approval helps establish a working price range and identify issues early, but the lender still needs to review the actual property once you have an accepted offer.
That property review can be especially important in Mission, where rural servicing, floodplain considerations, acreages, outbuildings, or unusual property features may affect the lender.
Before You Shop
I want these pieces understood first.
Income and employment
Credit and debts
Down payment and source of funds
Approximate purchase price
Expected housing costs
The Property Matters Too
Getting approved as a buyer does not mean every Mission property is automatically financeable.
Once you have an accepted offer, the lender needs to be comfortable with both you and the property being used as security for the mortgage.
Condos and townhomes
The lender may consider strata fees, insurance, building details, and other information about the strata alongside your application.
Detached homes
Condition, value, property taxes, renovations, suites, slopes, and retaining walls can all affect the lender's review.
Rural homes and acreages
Wells, septic systems, access, land size, outbuildings, zoning, insurance, and property use may require a more detailed review.
Once Your Offer Is Accepted
This is where the pre-approval becomes a real mortgage application.
The lender now knows the exact property, purchase price, taxes, strata costs when applicable, and other details that were not known during the pre-approval.
This is why the financing condition can be so important. It gives us time to confirm that the mortgage works with the actual home you are buying.
What gets reviewed now
The purchase contract
Property details
Updated income and debt information
Down payment documentation
Any lender conditions that still need to be satisfied
First-Time Buyer Programs
Use the programs that fit, but plan the withdrawals too.
First-time buyer programs can help with the purchase, but timing, eligibility, documentation, and how the funds move into the transaction all matter.
First Home Savings Account
An FHSA may be part of your down payment strategy if you are eligible and have funds available to withdraw.
Home Buyers' Plan
Eligible buyers may be able to use qualifying RRSP funds toward a home purchase, with repayment rules to understand afterward.
Property transfer tax and other benefits
First-time buyers may qualify for certain tax or program benefits depending on the purchase and their circumstances.
A Mission Example
The purchase price is only part of the first-home budget.
Imagine a first-time buyer looking at a $650,000 property in Mission with $50,000 available for the down payment.
Before deciding the purchase works, I would also want to know what cash needs to remain for closing, what the monthly housing costs will be, and whether the property brings any additional servicing or maintenance costs.
The goal is not simply getting into the home. It is making sure the mortgage and the property are manageable once you are living there.
Example Only
One possible starting point
This is a simplified illustration only. Mortgage insurance, qualification, closing costs, taxes, lender requirements, and available programs depend on the actual purchase.
What I'd Look at Next
Now we decide whether the home fits the budget.
Does the monthly payment fit comfortably?
Are strata fees or additional property costs involved?
Is there enough cash left after closing?
Has the specific property been reviewed by the lender?
Helpful Next Steps
Start with the first-home question you need answered.
You do not need to learn the entire mortgage process at once. Start with the part that matters for your next decision.
Help Me Plan My First Home- Mortgage ToolDown Payment CalculatorSee how the down payment changes at different purchase prices.
- Mortgage ToolClosing Cost CalculatorEstimate some of the additional cash you may need around completion.
- Mortgage MinuteWhat Is a Mortgage Pre-Approval?Understand what a pre-approval tells you and what still needs to happen later.
- Home Buying ProcessThe Home Buying ProcessFollow the mortgage and purchase process from planning through completion.
- Local Buying GuideBuying in MissionExplore Mission neighbourhoods, property types, rural homes, water-adjacent properties, and mortgage questions before making an offer.
- Mortgage GuideFirst-Time Home BuyersGo deeper into down payment, qualification, programs, and preparing for your first purchase.
Frequently Asked Questions
First-time home buyer questions in Mission
These are some of the practical mortgage questions that often come up before and during a first home purchase.
First-Time Home Buyer Help in Mission
You do not need to have everything figured out before we talk.
If buying your first home in Mission is something you are thinking about, we can start with the numbers you already know and work out what still needs to happen.
You can reach out before you are ready to make an offer. In many cases, that is the best time to start.
Help Me Plan My First HomeWhat We Can Work Through
A realistic purchase price
How much cash you may need
What the lender will want to review
What to have ready before making an offer